Advertisement
Tokenization Infrastructure
Share
AK
Senior English Editor


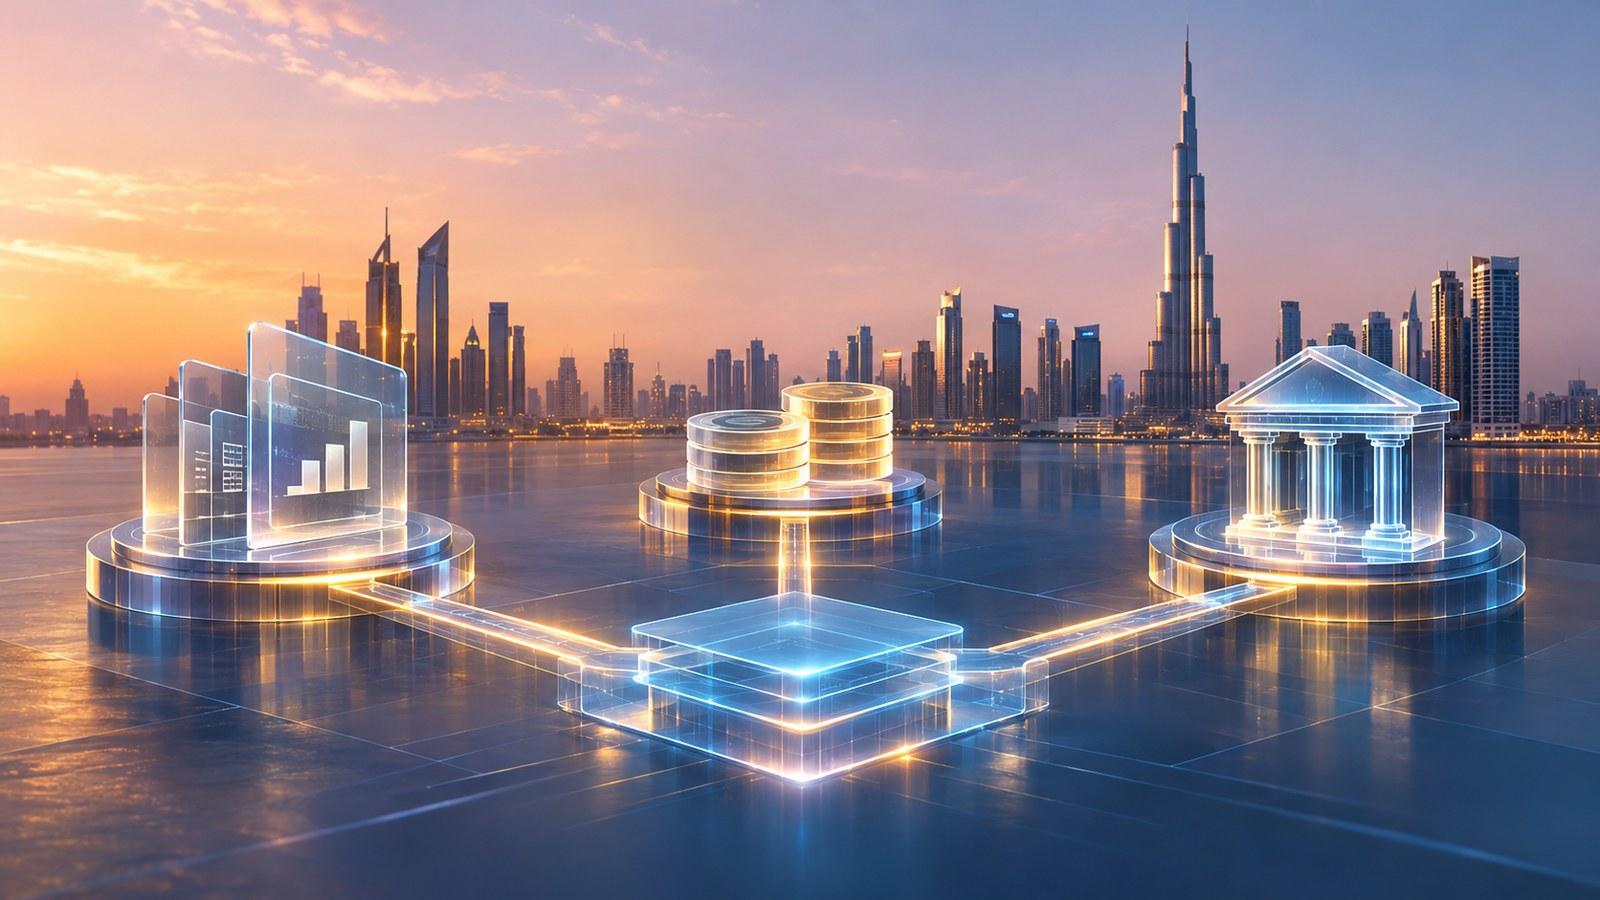
The DFSA's white paper 'Scaling Tokenization: The Road Ahead' identifies the convergence of tokenized assets, digital money, and banking infrastructure as the critical next step for the UAE's tokenization ambitions, moving beyond individual asset issuance toward a fully connected transaction lifecycle.
The UAE’s tokenization ambitions are entering a more demanding phase.
The question is no longer simply whether financial assets can be represented on a blockchain. It is whether the different parts of a financial transaction can work together once those assets move on-chain.
Consider an investor looking to purchase a tokenized bond or fund. The asset is issued on one blockchain. The digital money needed to pay for it operates on another network, or perhaps remains within a conventional banking system. Meanwhile, the investor has an existing relationship with a bank responsible for identifying the customer, facilitating payments and potentially providing custody or other financial services.
For that transaction to happen smoothly, all three sides must connect. The asset platform must recognize the payment. The settlement system must transfer the correct amount of money. The bank must be able to verify the investor and support the transaction under clear legal and operational arrangements.
This is the next test for tokenization: moving beyond the digitization of individual assets toward a financial market in which assets, money and institutions can interact.
A new white paper published by the Dubai Financial Services Authority (DFSA), Scaling Tokenization: The Road Ahead, examines the conditions required to make that transition. Drawing on structured interviews with BlackRock, Ripple, Robinhood, Standard Chartered and Soter Insure, alongside regulatory and market research, the report identifies several challenges that extend well beyond the technology used to issue tokens.
Its findings point to a broader question for the UAE. Can the country turn its growing range of digital asset initiatives into connected financial infrastructure that banks, institutions and investors can use across the entire transaction lifecycle?
Tokenization has made it possible to represent financial assets on blockchain networks, potentially enabling more flexible issuance, transfer and settlement. But an asset's presence on-chain does not, by itself, create a functioning financial market.
Every purchase still requires two sides of the same transaction: the transfer of the asset and the transfer of payment.
In traditional markets, these processes are supported by established institutions, payment systems and settlement arrangements. In tokenized markets, however, the asset and the money used to purchase it may exist on entirely different infrastructures. Connecting them requires more than a technical bridge between networks. The parties involved must also agree on how payment is made, when ownership changes, which records are authoritative and what happens if something goes wrong.
The DFSA identifies the convergence of tokenized assets and digital money as a key condition for scaling tokenized financial markets. Potential settlement instruments include regulated stablecoins, tokenized commercial bank deposits and wholesale central bank money.
Each offers a different route for bringing money into digital financial infrastructure. Stablecoins can facilitate transfers on public blockchain networks, while tokenized deposits could allow commercial bank money to move through digital platforms. Wholesale central bank money represents another potential settlement model for institutional markets.
The objective is not simply to create more forms of digital currency. It is to ensure that the money used in a transaction is trusted, accessible and compatible with the infrastructure handling the asset.
This is particularly relevant to atomic settlement, where the transfer of an asset and its corresponding payment occur simultaneously. Such arrangements could reduce the risk that one party delivers an asset without receiving payment. But the DFSA also highlights the need to consider liquidity, pre-funding and the role of netting and central clearing. Faster settlement does not automatically mean more efficient markets if participants must lock up substantial amounts of capital to complete transactions.
The real challenge, therefore, is to connect the asset and the payment in a way that improves the transaction without creating new operational or liquidity constraints.
Even as tokenized markets develop, the bank remains an important part of the transaction.
An investor does not necessarily want to abandon an existing banking relationship to purchase a digital asset. The bank may still be the institution that knows the customer, performs identity checks, provides access to funds and supports payments. Depending on the arrangement, it may also provide custody or connect the investor to a regulated trading platform.
This creates a practical requirement for tokenized markets: they must be able to interact with the institutions that already serve investors.
The DFSA report points to developments in which traditional banking money is being adapted for blockchain-based environments. JPMorgan, for example, has developed deposit tokens representing commercial bank deposits, with its JPMD token made available to institutional clients on Coinbase's Base network in November 2025. The report also discusses the role of established financial institutions, including Standard Chartered, in the development of digital asset infrastructure and tokenized collateral initiatives.
These developments illustrate how banks can extend their services into digital markets rather than simply operate alongside them. But connecting a bank to a blockchain-based transaction involves more than allowing money to move between systems. The bank must be able to establish who is participating, understand the nature of the asset and payment, and determine how its responsibilities apply when the transaction takes place across different infrastructures.
Custody is another essential part of this relationship.
Holding a token is not necessarily equivalent to holding a conventional security through a traditional custody arrangement. Institutions need clarity over the legal ownership of an asset, the control of private keys, the segregation of client holdings and the treatment of assets if a custodian or service provider becomes insolvent.
The DFSA stresses that institutional-grade custody must extend beyond protecting private keys. It also requires reliable ownership records, reconciliation between on-chain and off-chain systems, governance arrangements, business continuity planning and clear procedures for corporate actions, protocol changes and key recovery.
These safeguards matter because an investor's relationship with a bank cannot simply end at the point where an asset is transferred to a blockchain. The responsibilities surrounding the asset must remain clear throughout its lifecycle.
Even if the asset, payment instrument and bank are individually operational, a transaction can still fail if their underlying systems cannot communicate.
Tokenized assets are being developed across public blockchains, permissioned networks and proprietary platforms operated by financial institutions. This creates a fragmented environment in which an asset issued on one network may not be readily accessible to investors, payment providers or custodians operating elsewhere.
The DFSA describes the risk as the creation of separate digital islands. If these environments remain disconnected, tokenization could reproduce the fragmentation it is expected to overcome, leaving institutions to navigate multiple systems with limited compatibility.
For the investor in our example, this is a practical problem. The asset platform needs to communicate with the payment network. The bank must be able to receive and process the relevant instructions. Custodians and other intermediaries need to maintain consistent records, while the institutions involved must be able to establish that the transaction has been completed and ownership has passed.
Technical interoperability is therefore only one part of the equation.
Standards such as ISO 20022, standardized token formats, application programming interfaces and secure communication protocols could help different systems exchange information and instructions. But the DFSA makes clear that interoperability also has operational, legal and regulatory dimensions.
For instance, a token may represent the asset itself, serve as the authoritative record of title or constitute a contractual claim linked to an asset recorded elsewhere. If an off-chain register remains the legally authoritative record, the blockchain transaction must be reconciled with it. The parties must also understand when settlement becomes final, whether a transaction can be reversed and how disputes or operational failures will be handled.
These questions become even more complex when the transaction involves institutions operating in different jurisdictions. A transfer that works technically across two networks is not necessarily sufficient if the legal rights attached to the asset are not recognized consistently.
This is where the UAE's opportunity becomes more significant.
The country has attracted digital asset businesses, developed regulatory frameworks and encouraged engagement between traditional financial institutions and blockchain companies. But the next measure of progress will not simply be how many tokenized products are issued or how many platforms operate in the market.
It will be whether these different participants can work together to support a complete financial transaction.
Within the Dubai International Financial Centre (DIFC), the establishment of the Digital Economy Court in 2021 and the introduction of the Digital Assets Law in 2024 form part of the legal foundations identified in the DFSA report. The report also points to DIFC's international financial community as a potential platform for bringing together institutions, technology providers, investors, regulators and standard-setters.
That convening role could be particularly important because no single institution can build a connected tokenized market on its own.
Asset issuers need platforms on which to create and distribute products. Investors need access through familiar and reliable channels. Banks need ways to connect customer relationships and payment services to digital asset infrastructure. Custodians must be able to protect holdings and maintain reliable records. Digital money providers need settlement instruments that can interact with the networks where assets are traded.
The UAE's challenge is to create an environment in which these participants can coordinate their activities under clear legal, regulatory and operational expectations.
This also means looking beyond domestic infrastructure. Tokenized markets are likely to involve assets, investors and service providers operating across borders. The DFSA acknowledges that detailed regulatory harmonization may be difficult to achieve in the near term, but greater consistency in legal, operational and technical standards could reduce fragmentation and make cross-border participation more predictable.
For an international financial center, the ability to connect different systems and jurisdictions could become as important as the ability to attract new digital asset businesses.
There is another condition that cannot be solved through infrastructure alone: demand.
A tokenized asset may be technically sound, legally structured and supported by a bank, but it still needs investors, trading activity and sufficient liquidity to become a viable market.
The DFSA describes this as a 'cold start' problem. Traditional financial markets already have established participants, settlement processes and infrastructure. Individual institutions may have little incentive to migrate to a new system unless it offers measurable benefits and enough other market participants are ready to use it.
This is why connecting the asset, money and bank matters commercially as well as technically. If investors cannot access tokenized products through familiar financial relationships, if payment requires complicated transfers between networks, or if assets cannot be traded easily across platforms, the potential efficiency gains may remain limited.
Network effects will be essential. Issuers, investors, banks, custodians, trading venues and settlement providers need to develop together. As participation grows, the market can become more useful to each group. Without that participation, even technically advanced platforms risk remaining isolated initiatives.
The DFSA's analysis also suggests that the market must balance faster, more flexible settlement with the liquidity requirements of participants. An infrastructure that enables transactions around the clock may offer advantages, but those benefits must be weighed against the capital required to fund transactions and the established efficiencies of netting and central clearing.
Ultimately, institutions will adopt tokenization at scale only if it makes financial activity more accessible, efficient or commercially attractive.
The DFSA's white paper does not prescribe a particular technological, regulatory or commercial model. Instead, it examines the conditions that could support responsible growth, while recognizing that the market remains fragmented and that different institutions and jurisdictions may take different approaches.
It also warns that greater connectivity can introduce new risks. As tokenized markets become more closely linked to traditional finance, dependencies involving custodians, settlement providers, smart contracts, cloud services and blockchain bridges could create additional channels for operational disruption or financial stress. The report considers the sector unlikely to pose a material financial stability risk at its current scale, while noting that the implications could grow as tokenization becomes more interconnected and is used across trading, settlement, collateral and funding.
For the UAE, this makes the next phase about more than issuing assets on-chain. It is about making sure the entire transaction works.
Can an investor purchase a tokenized product through an accessible and trusted financial channel? Can the bank serving that investor connect to the platform where the asset is issued? Can payment be made using reliable digital money, even when the asset and settlement instrument operate on different networks? Can ownership be established, custody maintained and settlement recognized under clear legal arrangements?
Those are the questions that will determine whether tokenization moves from individual projects to a functioning financial market.
The UAE has an opportunity to help build that connection by bringing together the institutions, infrastructure providers and regulatory frameworks required to make it work. The real test will be whether an investor can move seamlessly between the asset, the money and the bank, without the boundaries between their respective systems becoming an obstacle.
Tokenization's next breakthrough may not come from creating another digital asset. It may come from making the financial system around that asset work as one.

Disclaimer of Warranty
The information provided in this article is for general informational purposes only. We make no warranties about the completeness, reliability, and accuracy of this information. Read full disclaimer

Editor's Picks
Binance After the $6.3B Hack: A Turning Point for the Exchange

Walid Abou Zaki

Nov 2, 2026

10 min
“One Financial System”: What OKX’s New Investors Are Backing
Walid Abou Zaki
Oct 8, 2026
6 min
When Assets Move—or Stop—Without Consent: The Limits of Crypto Wallet Control
Walid Abou Zaki
Sep 29, 2026
6 min
Read More Articles

In the Same Space
Commercial Bank of Dubai (CBD) Completes Wholesale Digital Dirham Transaction With Bank of China Through UAE's Jisr
Anna K.
Nov 10, 2026
3 min

VARA and Mastercard Partner to Support the Future of Digital Assets in Dubai
News Desk
Nov 10, 2026
3 min
What If Courts Could Freeze Crypto Assets With a Ruling? Dubai Has a Plan
News Desk
Nov 9, 2026
9 min
Dubai-Built Crypto Attention Platform Uses AI to Track Market Narratives
News Desk
Nov 5, 2026
6 min