Advertisement
Regulation & Policy
Share
SN
Senior English Editor


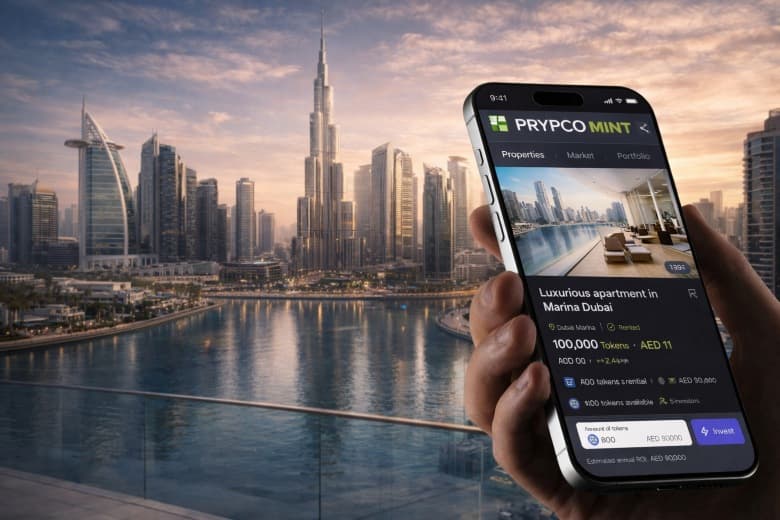
VARA has expanded PRYPCO FZE's authorization to include Category 1 Virtual Asset Issuance alongside its existing Broker-Dealer Services, positioning the company to pursue secondary trading, market-making, and collateral-based financing within Dubai's tokenized real estate market.
Dubai's Virtual Assets Regulatory Authority (VARA) has expanded PRYPCO's regulatory authorization to include Category 1 Virtual Asset Issuance alongside its existing Broker-Dealer Services permission, strengthening the company's position as Dubai's tokenized real estate market moves beyond fractional ownership toward a broader financial ecosystem.
The expanded authorization, now reflected in VARA's public register, permits PRYPCO FZE to provide regulated issuance and broker-dealer services to retail, qualified, and institutional investors, subject to applicable regulatory conditions.
The development comes as Dubai's real estate tokenization initiative moves beyond token issuance and investor access toward secondary-market liquidity, collateralization, market-making and the potential financial applications of tokenized ownership.
For PRYPCO, which operates the investor-facing platform within the Dubai Land Department's (DLD) real estate tokenization initiative, the broader opportunity lies in developing a business model that extends beyond the initial property investment marketplace.
Since the launch of Dubai's real estate tokenization initiative in May 2025, PRYPCO Mint has operated within a regulated pilot designed to test the digital representation and distribution of fractional property ownership.
The first phase demonstrated investor demand, with 10 properties attracting AED 18.65 million in investment from more than 2,600 participants, according to PRYPCO's October 2026 research report, Building Liquidity in Tokenized Real Estate.
The introduction of secondary-market trading in February 2026 marked another milestone, allowing investors to buy and sell existing tokenized property interests rather than relying solely on the eventual sale of the underlying property.
As Unlock Blockchain reported in its coverage of the PRYPCO Mint secondary-market launch, the opening of a secondary marketplace did not automatically make real estate liquid. It introduced a mechanism through which liquidity could develop, depending on actual market demand, pricing and trading activity.
PRYPCO's focus on issuance and distribution comes against this background, as the company looks to build on its role in the pilot while the market develops. The scope of its future activities, however, will depend on the permissions required for each service and the infrastructure needed to support it.
In its report, Building Liquidity in Tokenized Real Estate, PRYPCO argues that fractional access alone will not determine the long-term success of real estate tokenization.
The report identifies seven components of a more developed market: settlement, valuation, market depth, market-making, cross-listing, interoperability and the ability to use tokenized assets as collateral.
These elements point toward a broader transformation in how property ownership interests could be traded and financed.
Traditionally, real estate investments involve relatively high transaction costs, lengthy ownership-transfer procedures and limited flexibility for investors seeking to release capital without selling an entire property. Tokenization can separate ownership into smaller interests, but creating a liquid market requires additional infrastructure.
Market-making could help investors find counterparties when natural buyers and sellers do not match, while collateralization could eventually allow investors to borrow against eligible tokenized property interests rather than sell them to access capital.
Neither development is automatic. Market-making requires participants willing to assume inventory risk, while collateral-based financing introduces valuation, lending and liquidation considerations.
PRYPCO's report acknowledges that the pilot has demonstrated the operation of secondary trading but has not yet established reliable exits under all market conditions.
The next phase therefore involves more than proving that tokenized real estate can be traded. It requires demonstrating whether the market can support sustained trading activity, dependable pricing and financing arrangements.
Despite PRYPCO's stated licensing position, the growth of Dubai's tokenized real estate market remains closely connected to the regulatory framework governing property ownership and the role of DLD.
The existing pilot operates through a model that connects digital asset transactions with legally recognized property ownership records. Expanding the number of properties, broadening investor participation and introducing additional market functions will require continued development of that framework.
A wider ecosystem could involve multiple licensed distributors, technology providers, financial institutions and liquidity participants operating around tokenized property interests.
Such expansion would mark a shift from a controlled pilot toward a more developed market structure. The challenge will be to preserve the legal certainty associated with Dubai's property registry while enabling the efficiency and flexibility expected from digital financial markets.
The roles of the participants also remain distinct. DLD provides the property-registry framework, PRYPCO operates the investor-facing platform, and Ctrl Alt has provided tokenization infrastructure for the initiative. PRYPCO's issuance authorization does not, by itself, establish that these technical responsibilities are changing.
PRYPCO's stated focus on issuance and distribution could also create opportunities to explore tokenized assets beyond its existing real estate investment products. In his LinkedIn post, El Am said the company intends to expand its asset classes, partnerships and institutional capital base.
The distinction between serving individual property investors and providing tokenized asset services to financial institutions is significant. Institutional participation could bring additional capital and support more sophisticated trading and financing arrangements, but it also brings requirements around governance, risk management, custody, valuation and operational resilience.
Whether PRYPCO develops these capabilities directly or through partnerships remains to be seen.
For Dubai, the broader significance extends beyond one company's regulatory authorization. The combination of regulated issuance, secondary-market access, legally recognized property interests and potential financing applications could help develop tokenized real estate into a more interconnected financial market.
The next test will be measured less by how quickly additional properties are tokenized and more by whether those tokens can circulate efficiently, attract sustained demand and support financial activity beyond their initial issuance.
As DLD's tokenization initiative develops, the central question is whether Dubai can move from demonstrating digital property ownership to establishing the liquidity and financial utility needed for tokenized real estate to operate at scale.

Disclaimer of Warranty
The information provided in this article is for general informational purposes only. We make no warranties about the completeness, reliability, and accuracy of this information. Read full disclaimer

Editor's Picks
In the Same Space
ADGM Publishes Dedicated Crypto Mining Guidance

News Desk

Oct 28, 2026

2 min
Alpaca Moves Closer to UAE Market Entry with Preliminary ADGM Approval
News Desk
Oct 26, 2026
3 min
Switzerland Approves First Retail Spot Bitcoin ETF
News Desk
Oct 21, 2026
4 min
Further Asset Management Brings Programmable Compliance to ADGM Tokenization
News Desk
Oct 28, 2026
4 min