Advertisement
Stablecoins & Payments
Share
WA
CEO & Editor-in-Chief


Circle has formally asked the European Commission to revise MiCA's mandatory bank-deposit reserve requirement, joining the ECB and ESCB in arguing that forcing stablecoin issuers to hold 30–60% of reserves in commercial banks increases counterparty risk rather than reducing it.
Europe entered the stablecoin era with a clear philosophy: regulate first, allow the market to develop second.
When the MiCA stablecoin rules became applicable in June 2024, the European Union had something no other major jurisdiction could claim at the time: a comprehensive legal framework governing how stablecoins could be issued, backed and offered across a single market.
The ambition was difficult to fault. Europe wanted consumer protection, financial stability and clear rules before stablecoins became large enough to challenge the existing monetary system.
But being first also meant making assumptions about an industry that was still evolving.
More than two years later, some of those assumptions are being tested — not only by companies that resisted MiCA from the beginning, but by the European Central Bank and, most recently, Circle, arguably the global stablecoin issuer that embraced the European framework most enthusiastically.
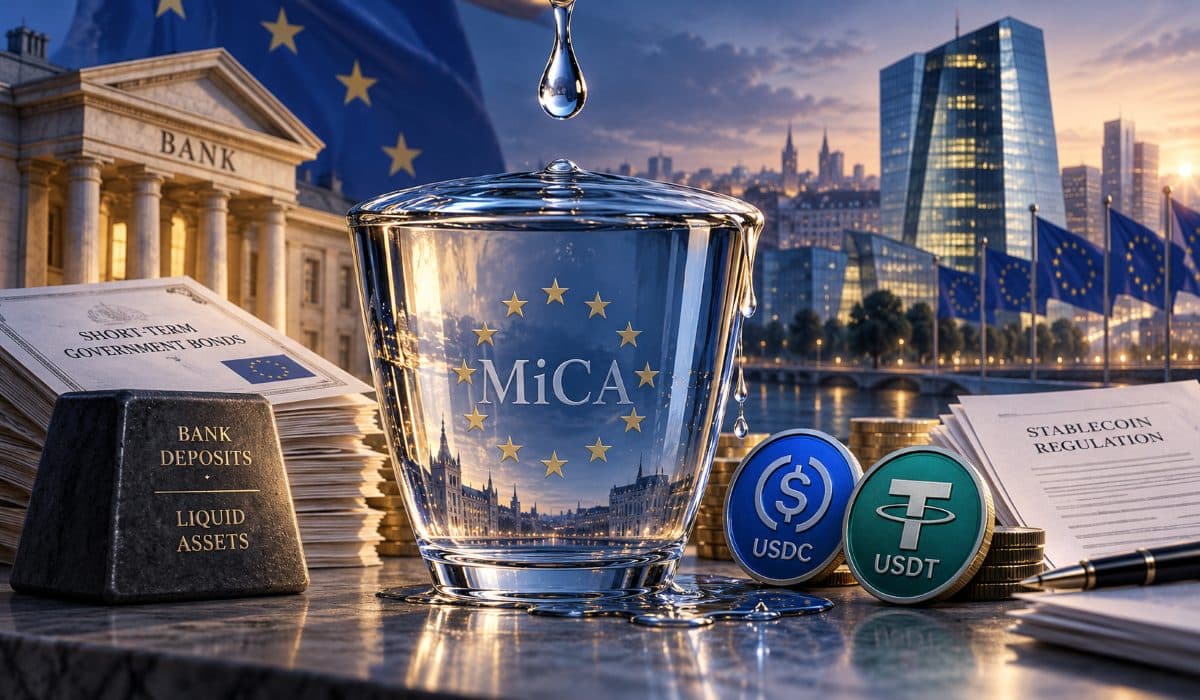
Circle's intervention may therefore be the last drop in an already full glass.
Europe's approach was deliberately conservative.
Among MiCA's safeguards, issuers of e-money tokens are required to maintain at least 30% of their reserve assets in commercial bank deposits. For significant e-money tokens, that requirement rises to 60%.
The objective was understandable: keep reserves liquid, place part of them within the regulated banking system and limit risks as stablecoins expanded.
MiCA's stablecoin provisions began applying on June 30, 2024, with the broader regulation following later that year.
But one of the world's largest stablecoin issuers immediately saw the reserve structure differently.
Tether CEO Paolo Ardoino repeatedly argued that forcing a large stablecoin issuer to hold as much as 60% of its reserves as uninsured commercial bank deposits could actually increase systemic risk rather than reduce it.
His argument was straightforward: government securities held directly by an issuer do not carry the same bank counterparty exposure as uninsured cash sitting inside a commercial bank.
The Silicon Valley Bank failure had already provided a real-world warning. Circle had $3.3 billion caught at SVB in March 2023, contributing to USDC temporarily losing its dollar peg.
In 2024, Ardoino argued that MiCA's requirements could make EU-regulated stablecoins more vulnerable and riskier to operate. His position was that issuers should be able to hold reserves primarily in highly liquid instruments such as Treasury bills rather than being forced to expose substantial amounts to commercial banks.
But the issue was not only about the quality of reserves. It was also about the capacity of the banking system expected to absorb them.
If a stablecoin is classified as significant, as much as 60% of its reserve assets may need to be held as bank deposits. At the same time, concentration limits restrict how much exposure an issuer can place with a single banking counterparty.
That raises a practical question: if an issuer is managing tens — or eventually hundreds — of billions of dollars, where exactly is all that money supposed to sit?
The question is not whether European banks are safe. It is how many banks have the balance-sheet capacity, risk appetite and operational infrastructure to absorb billions of dollars in reserves backing a stablecoin that can face large redemptions at any time.
This is no longer a theoretical concern. In its latest MiCA review response, Circle warned that deposit concentration limits could force large issuers to maintain reserve relationships with dozens of different banks, increasing operational complexity rather than reducing it.
At that point, the debate becomes broader than bank deposits versus Treasury bills. The real question is whether MiCA’s original reserve architecture was designed to accommodate a truly global stablecoin at scale.
However, Europe moved ahead.
And Tether did not.
The divergence quickly became visible.
Circle chose compliance.
On July 1, 2024, Circle announced that it had become the first global stablecoin issuer to comply with MiCA after its French entity obtained an Electronic Money Institution license. USDC and EURC could consequently be issued within the EU under the new framework.
Tether chose another path.
USDT remained outside MiCA's authorization structure, and European regulators subsequently tightened implementation. In January 2025, ESMA instructed national authorities to ensure crypto service providers stopped offering services that constituted an offer or admission to trading of non-compliant stablecoins, with compliance expected no later than the end of the first quarter.
The market adjusted.
Major European platforms removed or restricted USDT trading, while compliant alternatives such as USDC gained a regulatory advantage. The European Systemic Risk Board later noted that major platforms removed non-compliant stablecoins, while some moved toward converting affected balances into MiCA-compliant USDC.
On paper, the MiCA stablecoin rules appeared to be working as designed.
Europe had established the rules. A major global issuer had complied. The world's largest stablecoin had effectively been pushed outside the regulated EU trading perimeter.
But regulation was only one part of the equation.
Liquidity, profitability and scale were another.
MiCA was never supposed to be merely a mechanism for replacing USDT with another dollar stablecoin.
Europe also wanted a stronger euro-denominated digital money ecosystem.
That ambition eventually moved beyond fintech companies and into Europe's banking establishment.
In September 2025, nine European banks announced an initiative to create a MiCA-compliant euro stablecoin. That initiative became Qivalis, headquartered in Amsterdam and seeking authorization under the supervision of the Dutch central bank.
The project expanded quickly.
By February 2026, its consortium included 12 banks. By May, another 25 had joined, bringing Qivalis to 37 financial institutions across 15 European countries.
It was a formidable institutional response: European banks, European regulation and a euro-denominated stablecoin designed from the beginning around MiCA.
Yet the underlying global market remained stubbornly different.
Qivalis itself acknowledges that more than 95% of global stablecoin supply remains dollar-denominated.
And Circle has now supplied another uncomfortable statistic.
Despite roughly 30 e-money tokens having been authorized under MiCA, Circle says only three of the world's top 25 stablecoins by market capitalization — USDC, USDG and EURC — are currently MiCA-regulated.
Europe had succeeded in creating regulated issuers.
That did not necessarily mean it had captured global stablecoin liquidity.
Perhaps the most significant challenge to the original MiCA reserve architecture did not come from Tether or the crypto industry.
It came from Europe's own central banking system.
The European Central Bank has acknowledged that MiCA's mandatory bank-deposit requirements can make stablecoin issuers less profitable while simultaneously creating another potential channel of contagion between stablecoins and commercial banks.
In June 2026, ECB Executive Board member Piero Cipollone explained the problem directly.
If stablecoin reserves are concentrated in bank deposits, a bank failure can threaten the stablecoin. If the stablecoin itself experiences a run, large reserve withdrawals can transmit stress back into the banking system.
The ECB even pointed to USDC's exposure to Silicon Valley Bank in 2023 as evidence of the first risk.
Then the position went further.
In its response to the European Commission's MiCA review, the European System of Central Banks — comprising the ECB and EU national central banks — recommended removing the mandatory minimum bank-deposit requirement.
Instead of requiring 30%, or 60% for significant issuers, to sit in banks, the central banks proposed focusing on assets capable of maturing within one to five working days.
That represented an important shift in the debate around the MiCA stablecoin rules.
The risk Tether had warned about from outside the framework was now being identified, through a financial-stability lens, from inside Europe's own central banking establishment.
And then came Circle.
On October 1, Circle published its response to the European Commission's MiCA review consultation.
Its intervention carries particular weight because Circle cannot easily be portrayed as an issuer trying to escape European regulation.
Circle embraced MiCA.
It obtained authorization. It structured USDC and EURC around the European framework. And it has described MiCA as giving Europe a genuine regulatory head start.
But after operating within that system, Circle is now asking Brussels to reconsider important parts of it.
Most notably, Circle argues that the mandatory bank-deposit requirement should change.
It says forcing issuers to hold 30% to 60% of reserves in commercial banks increases exposure to banking-sector credit and counterparty risk. Like the European central banking system, Circle favors moving away from a rigid deposit ratio toward a more flexible liquidity-based approach.
Circle is also challenging restrictions affecting reserve concentration and proposing a recognition framework for stablecoins regulated outside the EU.
Its position on foreign stablecoins could prove particularly consequential.
Rather than leaving much of global stablecoin liquidity outside the European regulatory perimeter, Circle proposes an equivalence and recognition regime under which foreign-regulated issuers could potentially gain European recognition, subject to regulatory equivalence and local requirements.
Circle, Tether and the ECB do not suddenly agree on stablecoin regulation.
They don't.
The ECB remains considerably more cautious than Circle about issues such as multi-issuance involving EU and non-EU entities.
But something fundamental has nevertheless changed.
Tether questioned the economics and risk structure of the model from outside.
The ECB questioned part of the same architecture from the perspective of financial stability.
Now Circle is questioning it after operating inside the framework.
At this point, one can almost imagine Paolo Ardoino watching the debate unfold and saying: “I told you!”
There is some justification for the sentiment.
Not because Tether has suddenly been proven right about every aspect of MiCA. It hasn't. But because one of its central objections — that forcing stablecoin reserves into commercial banks could introduce risk rather than simply eliminate it — is no longer an argument coming only from Tether.
That changes the debate.
Europe deserves credit for moving before almost every other major market.
MiCA created legal certainty at a time when much of the world was still debating whether stablecoins should be treated as payments, securities, banking products or something entirely new.
But regulatory leadership and market leadership are not necessarily the same thing.
Europe chose to protect the existing financial architecture before stablecoins reached scale within its borders. That reduced certain risks, but it may also have made it harder for stablecoin businesses operating under MiCA to compete with models developing elsewhere.
The ECB itself has raised the profitability issue.
Circle is pointing to liquidity and counterparty constraints.
Tether had raised the banking-risk question from the beginning.
And the continued dominance of dollar-denominated stablecoins demonstrates the scale challenge.
Meanwhile, the United States has moved from years of regulatory uncertainty toward a federal stablecoin framework, increasing competitive pressure on Europe.
This is where the MiCA review becomes more than a routine legislative exercise.
The European Commission opened its consultation to determine whether MiCA remains fit for purpose following its initial implementation and developments in global markets. The review could ultimately lead to proposals to amend the regulation.
The question facing Brussels is therefore no longer whether stablecoins should be regulated.
That battle is largely over.
The harder question is how much conservatism Europe can afford when digital money operates in a global market where liquidity, capital and users can move elsewhere almost instantly.
Tether's objections two years ago could easily be interpreted as the complaints of an issuer unwilling to conform to Europe's rules.
That explanation is harder to maintain today.
When Europe's own central banking system questions the same reserve mechanism, and when Circle — one of MiCA's clearest stablecoin success stories — asks for it to be changed, Brussels has to consider whether the problem lies only with companies unwilling to adapt, or partly with rules designed before their consequences could be tested at scale.
Circle may therefore have added the last drop to the glass.
MiCA gave Europe the advantage of being first.
The MiCA review will show whether Europe is prepared to accept the price of having been too conservative — and whether it can change course before more of the global stablecoin market develops beyond its reach.

Disclaimer of Warranty
The information provided in this article is for general informational purposes only. We make no warranties about the completeness, reliability, and accuracy of this information. Read full disclaimer

Editor's Picks

When Assets Move—or Stop—Without Consent: The Limits of Crypto Wallet Control

Walid Abou Zaki

Sep 29, 2026

6 min

Where Do the Dollars Behind the UAE’s Crypto Economy Sit?
Anna K.
Sep 21, 2026
9 min
As U.S. Crypto Legislation Stalls, Circle Launches Its Own Financial Network
Walid Abou Zaki
Sep 16, 2026
9 min
Read More Articles

In the Same Space
Citi and Coinbase Put Stablecoins Behind Corporate Payments
News Desk
Sep 29, 2026
5 min
ESMA Proposes New DeFi Gateway Rules Under MiCA Review
News Desk
Oct 1, 2026
4 min
Mashreq and Citi Complete Live Tokenized Payment on Swift’s Blockchain Ledger
News Desk
Sep 30, 2026
3 min
EBA Urges EU to Regulate Crypto Lending and DeFi Under MiCA
News Desk
Sep 25, 2026
4 min